Archive: market commentary from December 2020, written by Imubit's Economic Engineering team. Prices, inventories and forecasts reflect conditions at the time.
In the October update we looked at distillate pricing relative to gasoline, a large determinant of refining operating strategy. At that time gasoline had finally started to lift away from diesel, as relentless distillate inventory builds were held off by large floating storage positions being taken out.
Since then there has been a series of consistent distillate draws. Together with good news on Covid-19 vaccines and a perceived cool winter outlook for the more populated parts of the country, those draws have rebuilt some confidence in distillates. Strength in distillates is not uncommon in winter, but the fundamentals behind this price action are open to question. Here are the possible drivers.
Will winter weather drive higher heating oil demand?
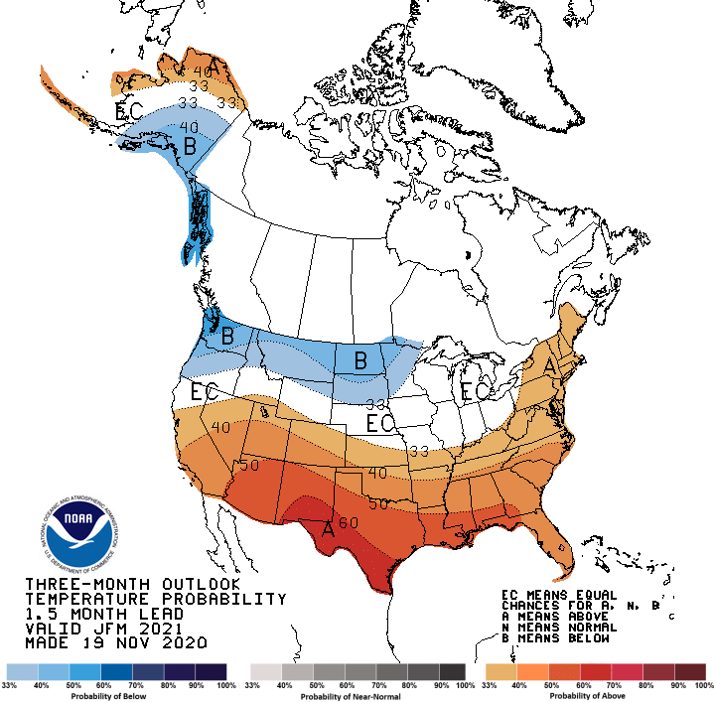
Figure 1: A cold winter? The NOAA Climate Prediction Center does not expect one.
Figure 1 shows the NOAA long-range forecast for January to March 2021. With a moderate La Niña in play, above-normal temperatures are forecast for most of the major population centers in the U.S., including the Northeast, where most heating oil is consumed. That suggests little weather-driven demand for distillates.
What about a recovery in air travel?
Covid-19 cases are surging in the U.S., and further restrictions and lockdowns are coming. Jet demand is unlikely to be anywhere near normal until a significant share of the population is vaccinated or infections fall in some other way. TSA passenger volumes are still at about 34% of the same period last year, based on the most recent full week.
Inventories are drawing
They are. EIA data show a draw of about 36.7 million barrels between September 11 and November 20. That was a substantial help, and it brought inventories back within the five-year range, as Figure 2 shows. It should be tempered by the fact that days of supply are still high, at 36.
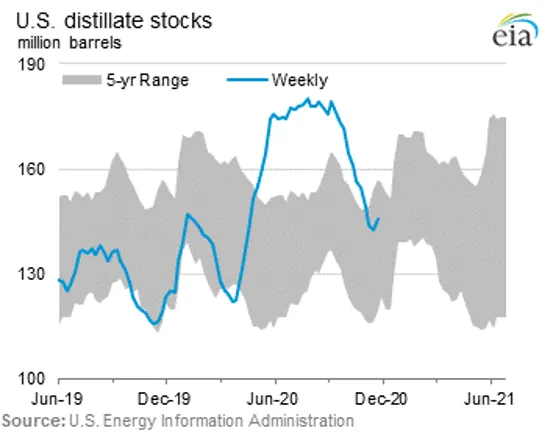
Figure 2: Distillate inventories against the five-year range. Source: EIA.
It is hard to find data showing how much of the draw came from loading ULSD onto VLCCs for export and floating storage, discussed in the October update. Our suspicion is that it was a contributor, at least a third of the draw if not more. A fall draw is typical with harvest demand in the Midwest, but perhaps not one as steep as this.
The gasoline to distillate spread
Figure 3 shows how the gasoline to distillate spread (G-D) has unfolded, measured as New York Harbor (NYH) RBOB gasoline less NYH heating oil. The top chart is the G-D spread and the bottom chart is the weekly change in distillate inventory, both from the EIA. The numbered points mark the events discussed below.
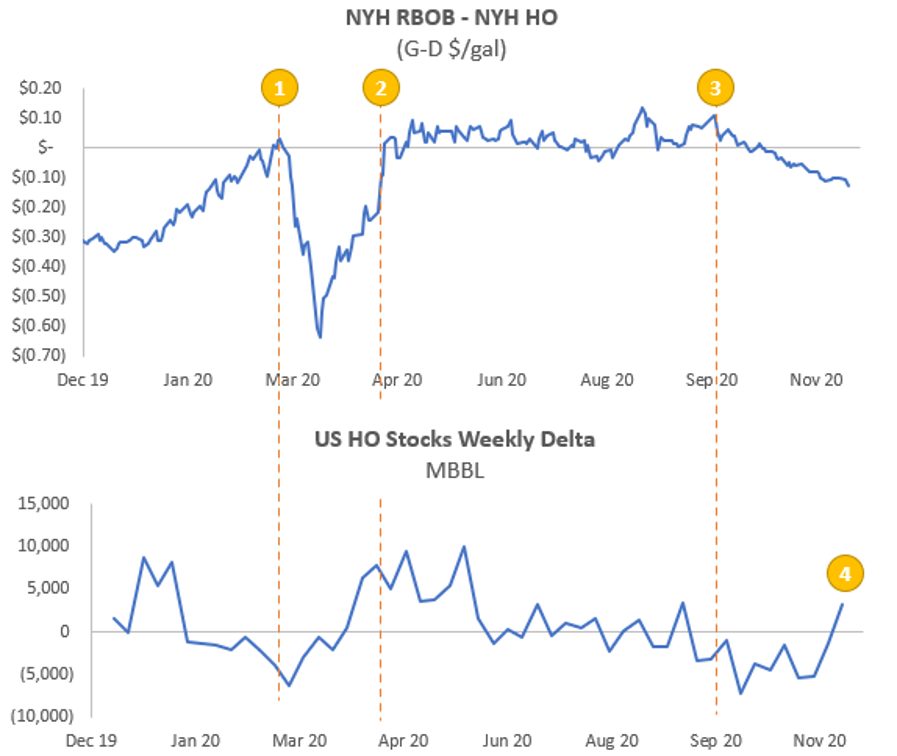
Figure 3: Top, NYH RBOB gasoline less NYH heating oil, front-month contract. Bottom, weekly change in heating oil stocks from the previous week. Data: EIA.
Up to point 1, it was business as usual. The G-D spread narrowed out of the distillate-favorable regime as the higher gasoline demand season approached. Then Covid-19 hit, hard.
Between points 1 and 2, the markets tried to find their feet. Gasoline crashed while distillate, for a moment, held up and became extremely favorable. At the bottom of that V, the distillate premium was hard to justify given the sudden fall in jet and kerosene demand, most of which would find its way into the ULSD pool. The market regained some sanity, and G-D moved closer to parity at point 2 as refiners balanced to the new normal.
Between points 2 and 3 was the pandemic steady state. Refiners adjusted runs to more economic levels as overproducing became financially punitive, and product pools became relatively balanced, with some draws on the gasoline side. It was surprising that G-D did not move further toward gasoline during this period.
A little before point 3, traders began loading VLCCs with ULSD for export and floating storage, and harvest season started in the Midwest. Harvest is a serious demand driver, and it shows clearly in inventories and demand, since trucks, tractors and combines all run on diesel. Inventories drew steadily between points 3 and 4, moving G-D toward diesel.
News of progress on vaccines also started to arrive, fueling a general rally in the hydrocarbon complex as traders' hopes for a strong economic recovery grew. ULSD demand is typically highly correlated with GDP, so an economic recovery should be fueled by diesel, and by jet as well.
At point 4, there is an inventory build and a good deal of discouraging Covid-19 news. Price action continues to point toward even more favorable distillate production, though this may be overdone. Either way, the distillate-favorable spread has boosted conversion and crude distillation incentives compared with the period between points 2 and 3.
Responding to the spread
Whether or not this price trend lasts, refiners have to respond quickly to these market changes. There is margin to be made as the spreads change, and every minute spent resisting the change or holding steady can be margin lost.
In refining, Imubit's Deep Learning Process Control® (DLPC®) models learn each unit's behavior from its own operating history and run in closed loop on top of the existing APC and DCS, inside limits set by plant engineers. They adjust crude and conversion units to the current economics minute by minute.